Fort Lauderdale Real Estate and Community News

Sept. 16, 2026

5 Highest Priced Sales in Fort Lauderdale


Fort Lauderdale Market Report

The 5 highest-priced home sales in Fort Lauderdale this year — and how they compare to Miami

Fort Lauderdale's luxury market has quietly put together an impressive 2026. Five estates have closed above $13 million so far this year, topped by a $34 million trade in Harbor Beach. Here's a look at each one, straight from MLS closed-sale data, and how the whole list compares to what Miami-Dade's top tier is doing.

The top 5

1

84 Isla Bahia Drive

84 Isla Bahia Drive, Fort Lauderdale View listing →
$34,000,000
Closed April 7, 2026 · Harbor Beach / Isla Bahia · 33316

A 300-foot Intracoastal point lot inside guard-gated Harbor Beach. Six bedrooms, eight full baths, four fireplaces, six wet bars, and a 90-foot infinity-edge pool across 11,714 square feet — about $2,902 per square foot. Listed at $34,950,000 and closed in just 23 days.

View the listing →
2

3052 N Atlantic Boulevard

3052 N Atlantic Boulevard, Fort Lauderdale View listing →
$26,000,000
Closed April 30, 2026 · Lauderdale Beach · 33308

100 feet of direct oceanfront, built by Bomar Builders in 2024. Five bedrooms, six full and four half baths across 10,289 square feet, with a floating infinity-edge pool facing the Atlantic. Sat on the market 135 days before closing, well under the $31 million ask.

View the listing →
3

632 2nd Key Drive

632 2nd Key Drive, Fort Lauderdale View listing →
$21,750,000
Closed June 4, 2026 · Sunrise Key · 33304

A near two-thirds-acre point lot with 355 feet of waterfront and a mega-yacht dock. Eight bedrooms, eight full and two half baths across 8,962 square feet, with a wine cellar, media room, gym, sauna, and a separate guest house.

View the listing →
4

1721 SE 11th Street

1721 SE 11th Street, Fort Lauderdale View listing →
$16,000,000
Closed August 11, 2026 · Rio Vista Isles · 33316

Eleven Rio: a brand-new, 2026-built tropical modern estate steps from the Lauderdale Yacht Club. Eight bedrooms, six full and two half baths across 7,030 square feet, with a sunset lounge, infinity pool, and full-house generator. Closed in just 37 days on market.

View the listing →
5

2880 NE 28th Street

2880 NE 28th Street, Fort Lauderdale View listing →
$13,900,000
Closed March 18, 2026 · Coral Ridge · 33306

A 2025-built modern resort estate one lot off the point, with 153 feet of no-wake-zone waterfront. Six bedrooms, eight baths, and 12,976 total square feet including a club room, home gym, spa with sauna and cold plunge, and a swim-up dock bar.

View the listing →

How Fort Lauderdale compares to Miami

Fort Lauderdale's luxury market is real and growing, but it's still a different scale than Miami-Dade's. Lining up each market's top 5 sales side by side, rank for rank, shows the gap plainly.

$111.65M
Fort Lauderdale's top 5 sales of 2026, combined
$369.45M
Miami-Dade's top 5 sales of 2025 alone, combined
The one number that says it all: Miami-Dade's fifth-highest sale of 2025 — $40 million for a Coral Gables estate — is still bigger than Fort Lauderdale's highest sale of 2026. It's a different market, and that gap is exactly why buyers priced out of Miami's ultra-prime tier keep landing here.
Thinking about buying or selling at any price point in Fort Lauderdale? I track this market closely, from waterfront trophy estates to first homes. Call or text me at (954) 982-8180, email bryan.gold@compass.com, or visit ftlaudhomes.com.
Sources: Fort Lauderdale sale prices, dates, and property details are from closed MLS data via ftlaudhomes.com. Some of these homes were listed and sold by other Compass and MLS-participating agents, not Bryan Gold; they're included here as market data, not as his own transactions.

Miami-Dade comparison data: MILLION Luxury, "Top 5 Most Expensive Home Sales in Miami-Dade (2025)"
Aug. 27, 2026

The New Condo Lending Rules Every Broward Buyer and Seller Should Know

Market news & financing

Condo Financing in Fort Lauderdale Just Got Harder. Here's What Changed and What to Do About It.

As of August 3, 2026, Fannie Mae and Freddie Mac stopped offering the shortcut review process on condo loans. If you own a condo, are selling one, or are shopping for one in Fort Lauderdale or anywhere in Broward, this affects how easy it is for a buyer to get financed — and it's worth understanding before it costs you a deal.

What actually changed

For loan applications dated August 3, 2026 or later, Fannie Mae no longer permits its Limited Review process, and Freddie Mac has eliminated the corresponding Streamlined Review option. This is spelled out in Fannie Mae's Lender Letter LL-2026-03.

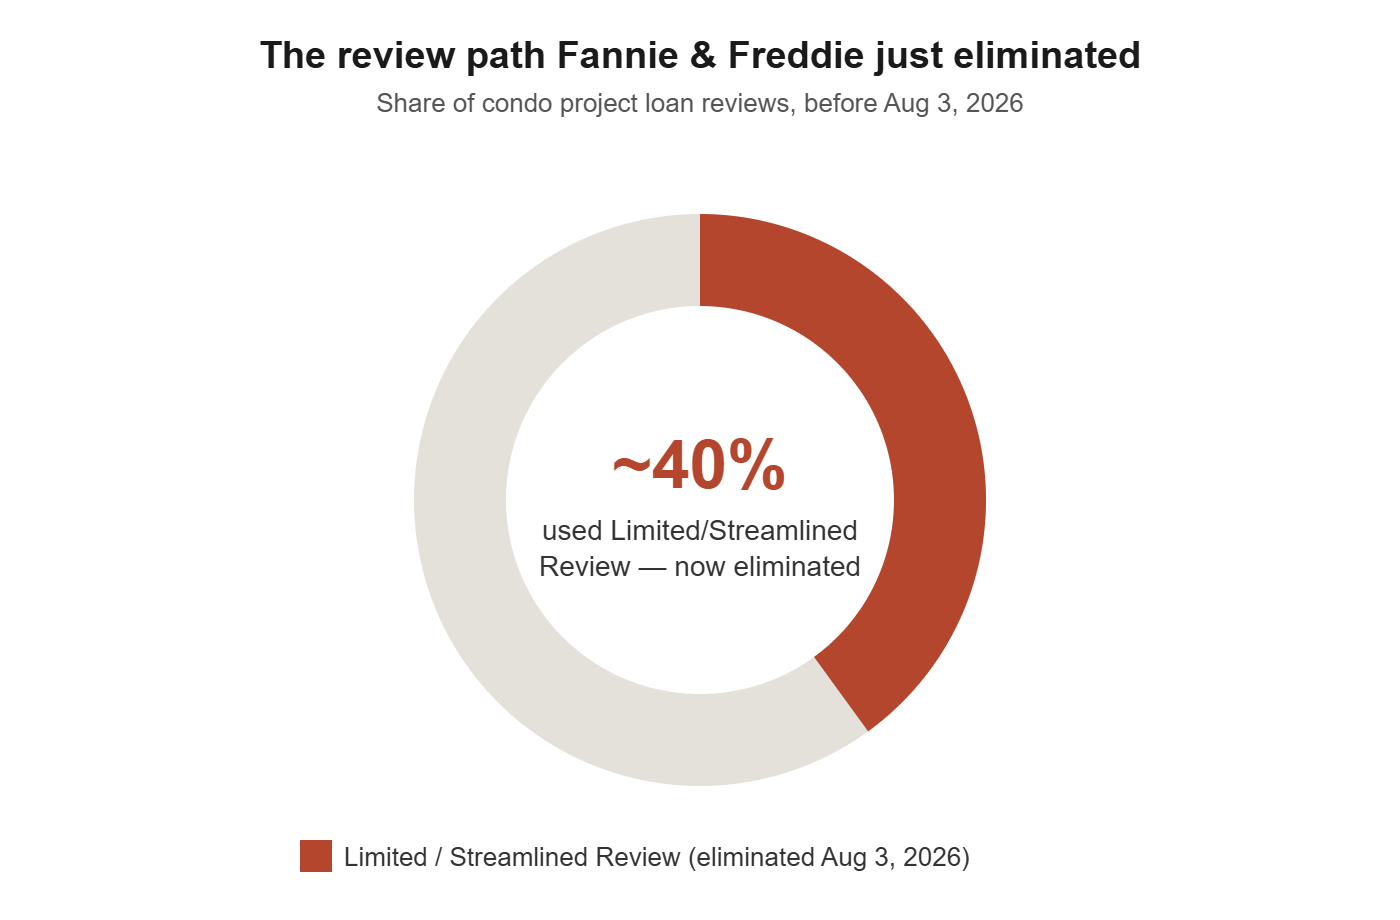
Those shortcut reviews used to let lenders skip a deep look at a building's finances for lower-risk loans — think smaller loan amounts or larger down payments. According to the Community Associations Institute, that shortcut path covered roughly 40% of all condo project reviews. It's gone now. Every condo loan gets the full review: reserve funding levels, milestone inspection compliance, management practices, insurance coverage, all of it, regardless of how much the buyer is putting down.

Source: Community Associations Institute, via reporting on Fannie Mae Lender Letter LL-2026-03

The Federal Housing Finance Agency, which oversees Fannie and Freddie, said the change comes from a documented correlation between underfunded condo associations and severe building failures. In Florida, that connection isn't abstract — it's the reason the state tightened condo safety law in the first place.

How we got here

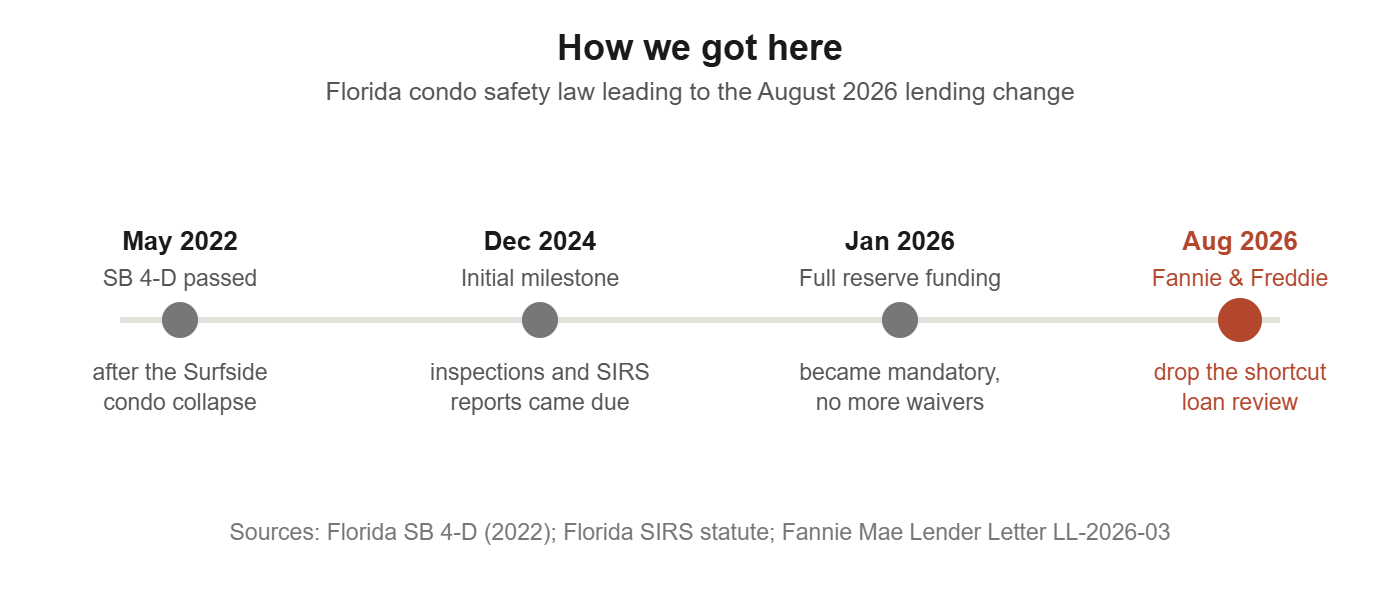
This didn't come out of nowhere. Florida has been tightening condo reserve and inspection requirements in stages since the Surfside collapse, and the August 3 lending change is the latest link in that chain.


Why this hits South Florida harder than most places

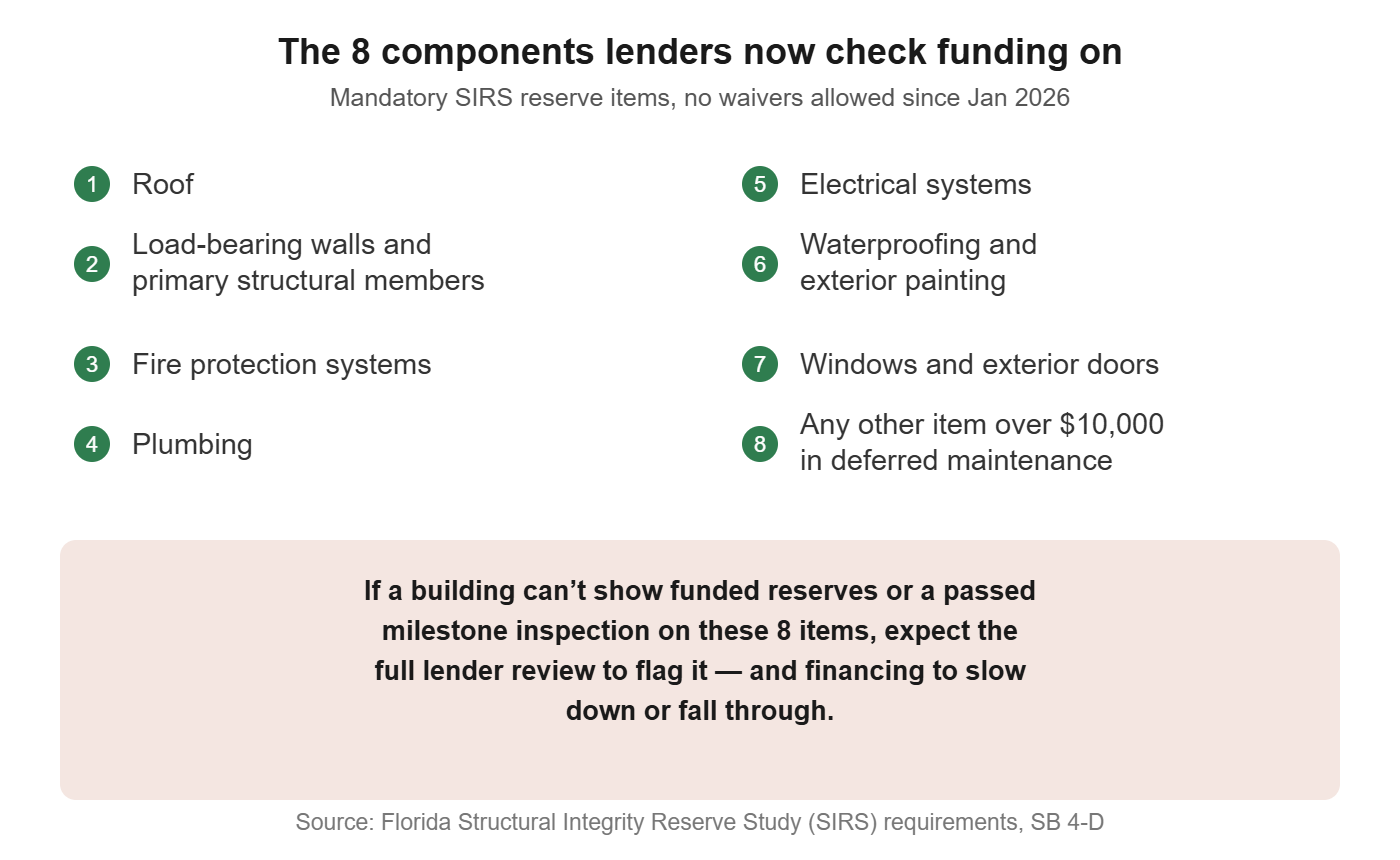
Conventional financing through Fannie and Freddie is the main path for most South Florida condo buyers, and that path just got a harder gate. Buildings that haven't funded reserves for the eight mandatory structural components, or haven't completed a required milestone inspection, are going to be harder — sometimes impossible — to finance a unit in, no matter how strong the buyer's financial profile is.


None of this means a building that fails full review is dead in the water. Portfolio and other non-standard loan programs exist for buildings that don't fit Fannie and Freddie's guidelines — they sit outside the conventional box, which is exactly the point. If a building you're buying or selling is getting flagged, it's worth a conversation before you assume the deal falls apart.

John Rosemary, VP of Mortgage Lending at CrossCountry Mortgage

John Rosemary

VP of Mortgage Lending, CrossCountry Mortgage · NMLS #203673

View profile · 954.588.3745

The market context: condos are already sitting longer

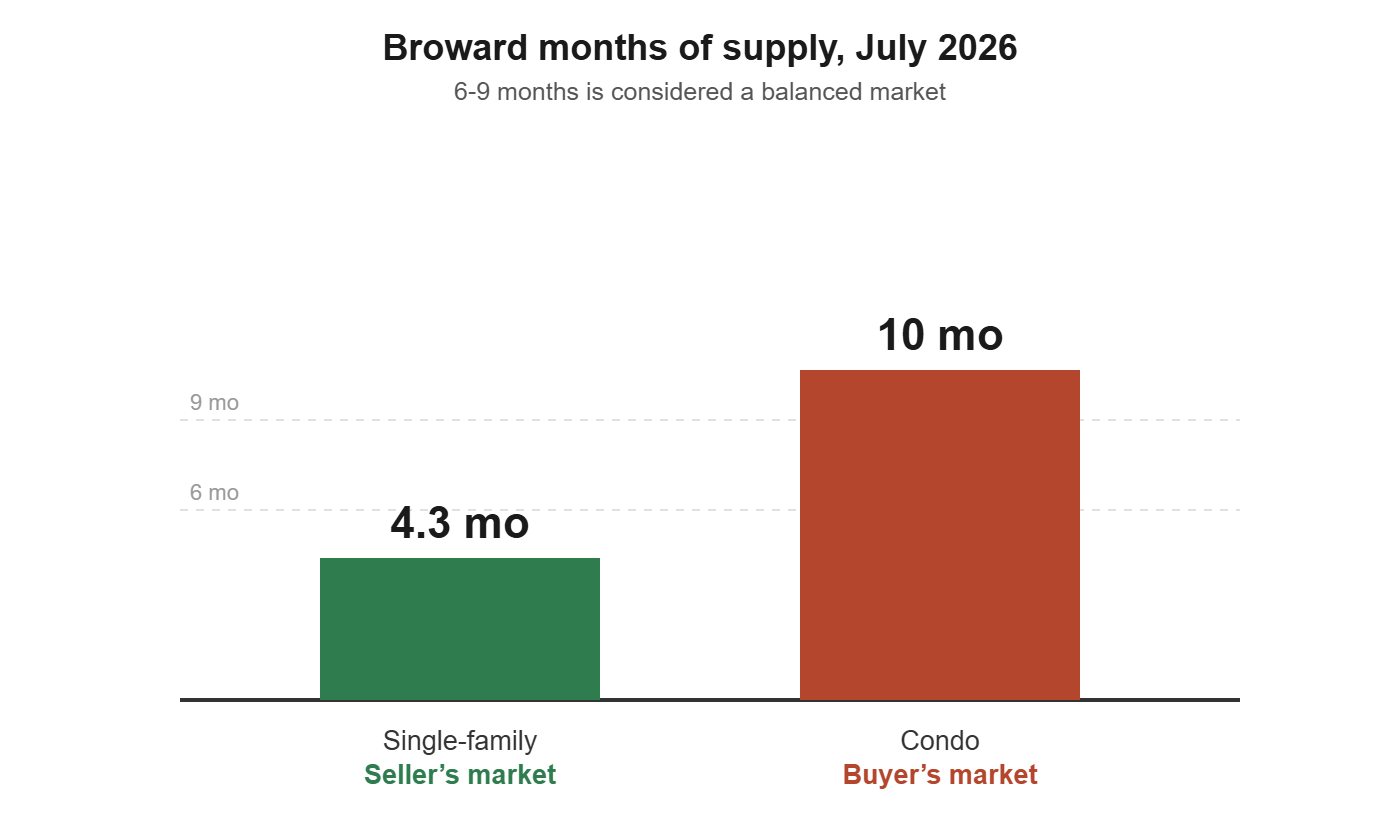
This is landing at a moment when Broward's condo market and its single-family market are moving in opposite directions. Broward single-family homes are at 4.3 months of supply, a seller's market. Condos are at 10 months of supply, solidly a buyer's market, and the median number of days to sell a condo climbed from 108 days a year ago to 122 days in July 2026.

Source: MIAMI REALTORS® + RWorld, July 2026 Broward statistics (Aug 17, 2026 release)

Tighter financing on top of a market that's already soft for condos means sellers in older buildings need to get ahead of the paperwork, not wait for a buyer's lender to find the gaps.

If you're selling a condo: pull your building's reserve study and milestone inspection documentation before you list, not after you get an offer. If the building is underfunded or hasn't completed a required inspection, know that going in — it changes who can realistically finance a purchase.

If you're buying a condo: ask for the reserve study and milestone inspection status before you get attached to a unit. A building that looks fine on a walkthrough can still be a financing dead end if its reserves aren't funded or its inspection is overdue. This is now a qualifying question, not a nice-to-know.

If you're weighing a specific building or want a second opinion on what a reserve study is actually telling you, reach out. I can help you read through it before you're deep into a contract.

Bryan Gold

Compass · ftlaudhomes.com

bryan.gold@compass.com · 954-982-8180

Sources

MIAMI REALTORS® + RWorld, "Broward County Total Home Sales Increase for Fifth Consecutive Month," Aug 17, 2026 — miamirealtors.com

TheStreet, "Fannie Mae condo shakeup could block your loan," Aug 2026 — thestreet.com

GoverningDocs, "2026 Fannie Mae Condo Rules: Reserves Up to 15%, Limited Review Gone" — governingdocs.dev

PropFusion, "Florida SIRS Requirements 2026" — propfusion.com

Rimkus, "Florida Senate Bill 4-D: What You Need to Know" — rimkus.com

Aug. 7, 2026

Broward Inventory Update


Fort Lauderdale Market Update

Broward's Inventory Surge Is Reversing. Here's What the Data Shows.

Active listings peaked at nearly 18,000 last spring. They've fallen in eleven of the last thirteen months — and that changes the leverage math for buyers and sellers heading into fall.

For most of 2025, the story in Broward County was straightforward: more listings hitting the market every month, homes sitting longer, buyers gaining room to negotiate. That story has quietly reversed. Active inventory peaked at 17,926 listings in May 2025 and has dropped in eleven of the last thirteen months, down to 14,870 by June 2026 — a 17% pullback from the peak, including four straight monthly declines from March through June.

Here's the twelve-month picture across the three numbers that actually move deals: how many homes are on the market, what they're listed for, and how long they sit before going under contract.

14,870
Active listings, June 2026 — down 16.2% year over year
$381,950
Median list price, June 2026 — down 4.5% year over year
82 days
Median days on market — down from an 89-day peak last September

Inventory: down 17% from last spring's peak

Broward County Active Listings
Monthly, July 2024 – June 2026

Source: Realtor.com Housing Inventory Core Metrics, via FRED (Federal Reserve Bank of St. Louis), series ACTLISCOU12011. Not seasonally adjusted.

Inventory in Broward built for two straight years after the ultra-tight 2022 market, when active listings bottomed out around 3,500. By last May it had climbed back to nearly 18,000 — the most choice buyers had seen in years. Since then it's been sliding, and not by accident: fewer new listings are hitting the market than are going under contract or getting pulled. That's a market cooling off from a buyer's high, not snapping back to 2022-style scarcity.

Prices: still easing, even as the shelf empties out

Broward County Median Listing Price
Monthly, July 2024 – June 2026

Source: Realtor.com Housing Inventory Core Metrics, via FRED, series MEDLISPRI12011. Not seasonally adjusted.

This is the part that surprises people: normally, shrinking inventory puts a floor under price. Broward's median list price hasn't gotten that memo yet. It's fallen every month since January, from $394,999 to $381,950 — a 3.3% drop in six months and 4.5% below June 2025. Sellers are still working through a backlog of 2025-era pricing that assumed more competition than currently exists. The inventory drop hasn't caught up to price expectations yet.

Days on market: cooling off from last fall's high

Broward County Median Days on Market
Monthly, July 2024 – June 2026

Source: Realtor.com Housing Inventory Core Metrics, via FRED, series MEDDAYONMAR12011. Not seasonally adjusted.

Homes are still sitting longer than they did in 2024, when the typical listing moved in the low 70s. But the number peaked at 89 days last September and has come down to 82 — including a dip to 73 in March. It's not a fast market. It's also not getting slower.

Put together: less competition among sellers, prices still adjusting down, and a pace that's stopped deteriorating. That's a market in the middle of resetting, not one moving cleanly in either direction.

What this means if you're on either side of a deal

Buying

You have fewer listings to choose from than you did a year ago, but prices are still soft and sellers haven't fully adjusted to the tighter shelf. Well-priced homes are the ones worth moving on quickly — the pullback in inventory means less competition is coming behind you than there was last spring.

Selling

Fewer competing listings works in your favor, but the price data says buyers still expect a discount from 2025 asking prices. List at what the current market — not last year's — will support, and you're less likely to be the listing still sitting in 90 days.

Want the numbers for your specific neighborhood or building?

County-level data tells you the direction. It won't tell you what's happening on your block. Send me the address and I'll pull the real comps.

Email Bryan
Bryan Gold · Compass · 954-982-8180 · ftlaudhomes.com

Source

Listing, price, and days-on-market figures for Broward County are from Realtor.com's housing inventory data, as published by the Federal Reserve Bank of St. Louis (active listings, median price, days on market). June 2026 is the most recent month available as of publication.

July 30, 2026

How Long Is It Taking to Sell a Home in Fort Lauderdale Right Now?


Fort Lauderdale Market Report — July 2026


Homes in Fort Lauderdale are sitting on the market for 99 days right now, up from 86 days a year ago.

List prices climbed too. Median list price is up to $699,000 this July, from $595,000 last year. Condos followed the same pattern, up to $559,000 from $479,000. On paper, that looks like a market getting more expensive. In practice, it's a market where sellers are asking for more and waiting longer to get it.

99 days
+13 days YoY
Median Days on Market
$699K
+17.5% YoY
Median List Price
$559K
+16.7% YoY
Median Condo List Price
Days on Market — July 2025 vs. July 2026
Median List Price — Single-Family Homes vs. Condos

Thirteen extra days on market is the gap between a seller who dictates terms and one who negotiates.

What this means if you're selling

A higher median list price doesn't mean your home is worth more automatically — it means the ceiling moved. Buyers are still doing the math on carrying costs, insurance, and rate, and 99 days of average exposure means overpriced listings are sitting long enough for buyers to notice, discount their offer, or walk. Price where the data says the market is today, not where it was twelve months ago.

What this means if you're buying

Thirteen extra days of average market time is leverage. Sellers who are past day 60 or 70 are more likely to negotiate on price, closing costs, or timeline than they were a year ago. That gap is worth using, especially on condos, where list prices rose just as fast as single-family homes.

Thinking about listing this fall, or want the current numbers for your specific neighborhood before you make a move?

Bryan Gold
Compass  ·  bryan.gold@compass.com  ·  954-982-8180  ·  ftlaudhomes.com

Posted in Selling Your Home
July 17, 2026

Zillow Showcase Listing


Zillow Showcase: Why I Put My Listings on It

Seller Tips  |  Bryan Gold, FT Laud Homes

Almost every buyer starts on Zillow. Not at an open house, not with a flyer — on their phone, scrolling a search results page, deciding in about a second and a half whether your house is worth tapping.

That means your listing's first showing isn't the one where somebody walks through the front door. It's the one on a screen. Zillow Showcase is a premium listing format built for that moment — and here's what it actually does for you.

Here's what one of my Showcase listings looks like on Zillow.

The numbers

Zillow's own data on Showcase listings compared to similar nearby listings without it:

  • About 75% more page views, saves, and shares.
  • Roughly 20% more likely to go pending within the first 14 days.
  • Sell for about 2% more, on average.

On a $600,000 Fort Lauderdale home, 2% is about $12,000. Zillow quotes a national average dollar figure that's lower, because the national average home costs less than ours does. Around here, the percentage is what matters.

Fair warning on those numbers: they're Zillow's, they're averages, and they compare similar listings rather than proving cause and effect. Showcase is not going to rescue an overpriced house. What it does is make sure the buyers who should see your home actually see it — and that the ones who tap in stay a while.

What a Showcase listing gets you

Four things, mainly:

  • Priority placement. Your listing appears higher in buyers' personalized search results and gets a larger, more prominent image on the map — the difference between being seen and being scrolled past.
  • An immersive tour instead of a photo roll. A Zillow 3D Home tour with an interactive floor plan. Click a room on the plan, jump to the photos taken there. Zillow's survey data says most buyers want a floor plan before they'll bother touring — and more than half have regretted wasting a Saturday on a house they'd have skipped if they'd seen the layout first. Showcase gives them that upfront, which means the people who do show up are the serious ones.
  • Dedicated email alerts. Your listing goes out to buyers Zillow has identified as actively hunting in your area — not a mass blast, a targeted one.
  • Scarcity, by design. Zillow caps Showcase at roughly 10% of the listings in any given market. Your house isn't competing with a page of listings that all look identical — and that cap is exactly why it's worth having.

What it costs you

Nothing extra. Showcase is part of how I market my listings — I cover it. There's no line item on your closing statement for it and no upsell conversation coming. If you list with me and your home qualifies, it goes on Showcase.

The honest version

Showcase is a tool, not magic. Price, condition, and photography still do most of the work. A well-priced house with great photos will sell without it, and a bad listing with it will still sit.

But when the difference between your house and the one down the street comes down to who noticed which listing first — and in this market, it often does — showing up bigger, higher, and with a real 3D tour is a genuine edge. It costs you nothing to have. There's no reason not to.

Thinking about selling? Let's talk about how your home gets marketed.

Bryan Gold  |  Compass Real Estate  |  Fort Lauderdale & South Florida

Call/Text (954) 982-8180 Email Bryan

Performance figures cited are published by Zillow Group and reflect averages across similar listings nationally; individual results vary. Showcase availability is subject to Zillow's market limits.

Posted in Selling Your Home
July 15, 2026

Put Your Offers in Writing


Put Every Offer in Writing — Even the Low Ones

Buyer Tips  |  Bryan Gold, FT Laud Homes

Watch the 90-second video version, or read on below.

If you take one thing from this post, take this: a verbal offer is easy to dismiss. A written offer starts a negotiation.

I see it all the time. A buyer floats a number over the phone — maybe a low one — and the seller or their agent puffs their chest out. "No way. Not even close." End of conversation. Nothing was ever really on the table, so nothing had to be taken seriously.

Things change when something is in writing.

A verbal offer isn't really an offer

Here's the part most buyers miss: the price is only one piece of an offer. A real offer also spells out things like:

  • Whether you're paying cash or financing
  • The financing contingency and what happens if the loan falls through
  • The inspection period and your right to walk away
  • Deposit, timelines, and closing terms

A number tossed out over the phone conveys none of that. A seller might reject "$450K" verbally but seriously consider $450K cash with a short inspection period and a quick close. They can't weigh what they can't see.

A real example from one of my listings

On one of my current listings, a buyer without an agent came in with a low offer. I could have brushed it off. Instead I said, let's write it up.

I put the low offer in writing and presented it to my seller. My seller countered. The buyer countered back. The seller countered again. The buyer came up. They met in the middle — and we're under contract today.

If that offer had stayed verbal, there would be no contract. The written offer is what forced a real response instead of a reflexive "no."

The psychology behind it

Sellers know what they'd actually accept — but they'll act like they want more, hoping you'll negotiate against yourself or back off because you "don't want to offend them." A written offer cuts through the posturing. It puts a real decision in front of them, and their counter tells you what the other side actually wants.

Worried a low offer will insult someone? It won't kill the deal. Silence kills deals. Paper starts them.

The bottom line

Put every offer in writing — even when it feels low, even when you think it won't go anywhere. That's how I work, on every deal.

Want an agent who puts your offers in writing and negotiates for real?

Bryan Gold  |  Compass Real Estate  |  Fort Lauderdale & South Florida

Call/Text (954) 982-8180 Email Bryan
Posted in Buying a Home
Sept. 5, 2025

Property Taxes, Homestead Exemption and Portability


Selling Your Homesteaded Home in Florida: What You Need to Know About Taxes

Seller Tips  |  Bryan Gold, FT Laud Homes

One of the biggest advantages of owning a primary residence in Florida is the Homestead Exemption. It lowers your property taxes while you live there — but what happens when you sell? Many homeowners are surprised to learn that selling a homesteaded property has both property tax and income tax considerations.

Property Taxes and the Homestead Exemption

Florida's Homestead Exemption reduces your home's assessed value by up to $50,000 for property tax purposes. It also locks in the "Save Our Homes" cap, which limits annual assessment increases to 3% or less.

When you sell your homesteaded property:

  • Your exemption ends with that property.
  • The buyer's assessed value resets to market value — which usually means their property taxes will be higher than yours were.
  • If you buy another primary residence in Florida, you may be able to port (transfer) your accumulated Save Our Homes savings to the new home, reducing its assessed value and your future property taxes.

Watch the clock: you must establish your new homestead within three tax years of abandoning the old one — and the clock runs from January 1 of the year you leave, not from your closing date. Sell in December and you've already used up most of a year.

Learn more at the Broward County Property Appraiser website →

Federal Income Taxes: The IRS Exclusion

At the federal level, the IRS offers a major benefit when you sell your primary residence. If the home was your primary residence for at least two of the last five years, you may qualify to exclude up to:

  • $250,000 of gain if you're single
  • $500,000 of gain if you're married filing jointly

If your profit falls under those limits, you won't owe federal capital gains tax on the sale.

What About State Income Tax?

Here's the good news: Florida has no state income tax. Even if you have taxable gain above the IRS exclusion limits, you only need to worry about federal taxes — not state income tax.

Special Considerations

  • Investment or rental use: If part of your home was used as a rental or for business, different rules may apply to that portion.
  • Portability deadline: Three tax years from January 1 of the year you abandon the old homestead — and you must apply by March 1 of the year you claim it. It doesn't transfer automatically.
  • Document your costs: Keep records of improvements and closing costs — they can reduce your taxable gain.

Bottom Line

Selling a homesteaded home in Florida comes with real tax advantages. You'll lose your exemption on the sold property, but portability lets you take your Save Our Homes savings with you when you buy again. And on the federal side, the primary residence exclusion helps many sellers avoid capital gains tax entirely.

If you're thinking about selling, talk with both a Realtor® and a tax professional before you list — the timing of your sale can affect what you keep.

Thinking about selling your South Florida home?

Bryan Gold  |  Compass Real Estate  |  Fort Lauderdale & South Florida

Call/Text (954) 982-8180 Email Bryan

This article is general information, not tax or legal advice. Consult a qualified tax professional about your specific situation.

Posted in Selling Your Home
Oct. 18, 2023

2024 New Conforming Loan Limits

The anticipation is over—2024 brings sensational news that will reshape your path to homeownership! 🚀 Get ready for a breakdown of the game-changing conforming loan limits that promise to make your housing dreams a reality! 🏡✨


🏠 **Single-Family Homes:** $750,000 (up from $726,200 in 2023)  

🏠🏠 **Two-Unit Properties:** $960,300 (up from $929,850 in 2023)  

🏠🏠🏠 **Three-Unit Properties:** $1,160,700 (up from $1,085,850 in 2023)  

🏠🏠🏠🏠 **Four-Unit Properties:** $1,442,500 (up from $1,396,800 in 2023)


These exciting adjustments spell out new possibilities for your homeownership journey. 🌈 Whether you're envisioning a dreamy single-family home or contemplating a savvy multi-unit investment, the expanded limits create a buffet of options! 🛤️💼


Seize this golden opportunity! Dive into the realm of financing options, and we're here to guide you every step of the way. 📞💬 Transform your homeownership dreams into a living reality!


Here's to a radiant and more budget-friendly 2024! 🥂🏠

Oct. 12, 2023

NAR's Evolution in Commission Rule

The National Association of Realtors® (NAR) has made a significant adjustment to its commission policy, known as the Participation Rule. This change now permits listing brokers to offer buyer brokers a compensation of $0 when listing a home in any of the 500 Realtor-affiliated MLSs across the U.S.


Previously, NAR's Participation Rule mandated listing brokers to provide buyer brokers with some form of commission, even if as minimal as one penny. With two class action lawsuits on the horizon, NAR has modified the rule's specifics.


According to NAR spokesperson Mantill Williams, "NAR’s MLS policy requires participants to communicate an offer of compensation to other MLS participants, and that offer can be any amount, including $0."


NAR insists that this alteration emphasizes transparency in commission dealings between brokers and clarifies that it doesn't mandate MLSs to change their data fields for $0 compensation.


**Ensuring Efficiency Amidst Change**


NAR asserts that its policies aim to efficiently distribute information for real estate transactions' benefit to both buyers and sellers. According to Mantill Williams, NAR spokesperson, these policies prevent brokerages from relying on inefficient, piecemeal information that could negatively impact their ability to serve clients and the U.S. economy.


Despite criticism, NAR maintains confidence that the upcoming trials will not sway the jury with any confusion. The association downplays the about-face, arguing that there's no evidence of the alleged price-fixing.


**NAR's Shifting Stance: From "Not Zero" to "Any Amount, Including $0"**


Historically, NAR asserted that listing brokers could offer buyer agents "as little as" one penny or one dollar for commission. Now, just before trial, they allow $0, prompting speculation about potential confusion in NAR's strategy.


This change has led some, like Redfin, to question NAR's interpretation, stating, "That is not our understanding of how NAR has interpreted their policy in the past and appears inconsistent with prior reporting."


As the real estate landscape undergoes these shifts, we'll continue to provide updates. Stay tuned for more developments.

Posted in Real Estate News
Oct. 4, 2023

Property Taxes in South Florida

Understanding Homestead Exemption and Property Taxes in South Florida


South Florida is a popular destination for homeowners due to its beautiful beaches, vibrant culture, and favorable climate. However, when it comes to owning property in the Sunshine State, it's essential to understand how property taxes and the homestead exemption work. In this blog post, we'll delve into the details of these crucial aspects of homeownership in South Florida.


What is Homestead Exemption?


The homestead exemption is a property tax relief program offered to permanent Florida residents who own and occupy their primary residence. This exemption provides eligible homeowners with a reduction in the assessed value of their property for tax purposes, ultimately lowering their property tax bills.


Here are some key points to understand about the homestead exemption in South Florida:


1. Eligibility Criteria:To qualify for the homestead exemption, you must meet certain criteria:

   - You must be a permanent Florida resident.

   - The property must be your primary residence as of January 1st of the tax year.

   - You must apply for the exemption between January 1st and March 1st of the tax year.


2. Exemption Benefits: The homestead exemption can provide significant benefits to homeowners. It reduces the assessed value of your property by up to $50,000, resulting in lower property taxes. For example, if your home is assessed at $300,000 and you qualify for the full $50,000 exemption, you will only pay property taxes on an assessed value of $250,000.


3. Save on Taxes: The homestead exemption can save homeowners hundreds or even thousands of dollars on their annual property tax bills, making homeownership in South Florida more affordable.


How Property Taxes Work in South Florida


Property taxes in South Florida are used to fund essential services such as schools, public safety, infrastructure, and local government operations. Here's a breakdown of how property taxes are calculated in the region:


1. Assessed Value: Property appraisers determine the assessed value of your property. This value serves as the basis for calculating your property taxes. It is important to note that the assessed value may increase by up to 3% per year under the "Save Our Homes" cap for homesteaded properties, even if the market value increases at a higher rate.


2. Millage Rate: Local governments set a millage rate, which is a tax rate per $1,000 of assessed value. The millage rate can vary between different counties and municipalities within South Florida.


3. Calculating Property Taxes: To calculate your property taxes, multiply the assessed value of your property by the applicable millage rate. For example, if your home's assessed value is $250,000 and the millage rate is 10, your annual property tax bill would be $2,500 (250,000 x 10 / 1,000).


4. Additional Taxes: In addition to regular property taxes, there may be additional taxes for specific purposes, such as school district taxes or special assessments for community improvements.


Understanding the homestead exemption and property taxes is essential for homeowners in South Florida. The homestead exemption can provide valuable tax savings, making homeownership more affordable for permanent residents. Additionally, knowing how property taxes are calculated helps homeowners budget for their annual tax bills.


If you're a homeowner in South Florida, take advantage of the homestead exemption to reduce your property taxes, and always stay informed about any changes in tax laws or rates in your local area. Being knowledgeable about these aspects of homeownership will help you make informed financial decisions and enjoy the benefits of living in this beautiful part of the Sunshine State.